Insurance Insights: The Cleary Insurance Blog
The Cleary Insurance blog covers insurance, risk management, and financial planning for New England businesses and individuals. Our team of licensed advisors and specialists publishes regular articles on commercial and personal coverage, employee benefits, life and financial planning, and insurance compliance. Browse recent articles below, or use the category filters to find topics relevant to your business or personal situation.
Risk Management Ideas
As 2022 begins its last quarter, now is a good to review various risk management ideas you may wish to consider and or implement for 2023. Risk Management consists of implementing polices, practices or procedures that reduce the odds of loss or the size of a loss once it occurs. An example of reducing odds of a loss, would be reviewing your employees driving records before you hire them and annually. The better your drivers, the lower the odds of a loss. In addition, training the drivers on what to do after a loss can make a big difference in the size of a loss. Do they know to not offer responsibility, take pictures, get names of other drivers, etc.
All clients want the lowest insurance premiums possible and using risk management practices is a great tool in having lower premiums due to having a more attractive loss history.
Most insurance carriers offer loss control and risk management services at no charge to the client. Consider 2023 as the year to make improvements in this important area of your company’s financial wellbeing. Contact your Cleary Insurance Account Executive to discuss risk management ideas.
Want a Health Boost? Listen to This Type of Music.
Posted by Alyssa Malmquist on August 31, 2022
If you’ve ever felt a surge of well-being while listening to classical music, you’re certainly not alone—and best of all, that doesn’t have to be a temporary feeling. Research indicates that this type of music offers plenty of long-term benefits when it comes to your health.
Improved heart health
Should Mozart and Strauss be part of your heart health strategy? That’s the conclusion of a German study that looked at the effects of classical music compared to other genres. A group of healthy participants listened to either pop music or classical music for just a few hours, and those in the latter group showed lower blood pressure and heart rate after listening.
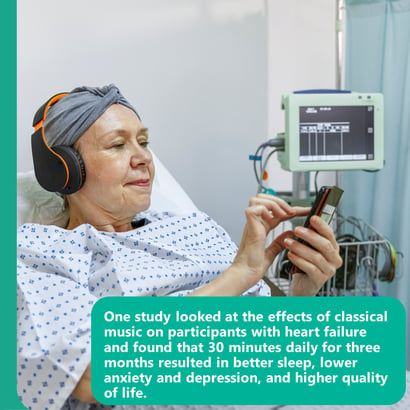
Even those who already have heart issues could see an advantage. Another study looked at the effects of classical music on participants with heart failure and found that 30 minutes daily for three months resulted in better sleep, lower anxiety and depression, and higher quality of life.
Better pain control
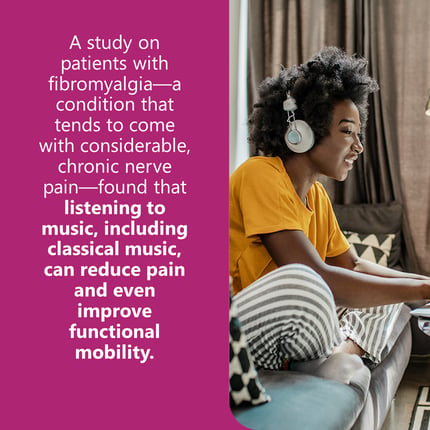
There’s an effect called “music-induced analgesia,” which means that music can actually reduce pain in a way that’s similar to pain medication. For example, a study on patients with fibromyalgia—a condition that tends to come with considerable, chronic nerve pain—found that listening to music, including classical music, can reduce pain and even improve functional mobility.
That study noted that the mechanism is likely related to how music boosts dopamine, one of the hormones related to feelings of well-being. When this happens, your brain may reduce pain signals.
Another study reports that classical music may have an effect on acute pain as well. Researchers found that people recovering from surgery were able to be prescribed lower doses of pain relievers when they listened to this type of music, and even tended to have shorter hospital stays.
More mental clarity
With a more comprehensive amount of mental quiet, it’s much easier to concentrate and focus on tasks at hand, and classical music can be a boon for providing that type of ease.
For example, research published in the Journal of Music Therapy looking at the effects of music written by Mozart versus “new age” music found that both types inspired feelings of thankfulness and love, but participants in the classical music group had substantially higher levels of mental quiet, awe, and wonder.
This seems to be true even for kids. A study from the Institute of Education at the University of London assessed the effects of classical music on children aged 7 to 10 and found that after just six listening sessions, they showed higher levels of concentration and self-discipline.
Lower stress
How does classical music stack up against other relaxation techniques? Quite well. One study, published in the journal PLoS One, recruited 60 women and split them into three groups: one that listened to the classical Miserere by composer Gregoria Allegri, one that enjoyed the sound of rippling water, and the last with no sound at all, only rest.
The three groups differed significantly in terms of stress response. While the music group had more stress than the water group while listening, it showed much faster recovery than the other groups. Researchers concluded that because of this, music should be seen as an intervention tool for stress management and stress-related health issues.
That last item is particularly important, because stress has been shown to contribute to a range of health issues, including low back pain, cardiovascular disease, even some cancers. Lowering stress levels in a way that helps you bounce back quickly from stressors can potentially mitigate these risks.
What about other music?
If you’re not a fan of classical music, good news: Other types of music have also been shown to be beneficial to your mental and physical health, especially if it’s music that makes you feel a deeper sense of relaxation or joy.
For instance, researchers at the University of California, Berkeley looked at the reactions of over 2,500 people to thousands of song samples, and found that multiple types of music prompt emotions like amusement, cheerfulness, desire, dreaminess, and triumph. Although they can also evoke feelings of sadness or annoyance, it depends on what type of music you choose.
The lead researcher noted that music is a universal language, but that we don’t always pay enough attention to what it’s saying and how it’s being understood. Taking the time to incorporate more music into your life—classical or otherwise—could be an important step toward learning this language and supporting your health along the way.
To learn more about physical wellness, plus a fresh perspective on overall health and wellness, download Allways eBook.
The Fed’s Inflation Fight and the Markets
Presented by: Matthew Clayson, Financial Advisor at Commonwealth Financial Group
Markets have been troubled. Open any brokerage or 401(K) statement and you are likely to see a page of red. It seems that nearly everything has gone precisely the wrong way: bonds are down, stocks are down, and gas prices (along with the price of nearly everything else we purchase) are up.
Fear and uncertainty abound, and the headlines foreshadowing the end of the world are not helping.
And yet…perspective matters.
There are three important points:
- While painful, what has occurred is a healthy and needed reaction to the withdrawal of liquidity.
- I am beginning to find more optimism in our monetary policy than I have in nearly three decades.
- This is not the time to react emotionally. Even if we are pushed into a recession, if history is any indication, we will likely be fine.
With that, let us begin.
Liquidity and monetary policy
As we’ve discussed in previous updates, the U.S. Federal Reserve is the Central Bank to the United States and, as the name states, is essentially the lender of last resort. The Fed (as it is colloquially referred) has very crude tools. It can:
- Signal what it’s going to do by talking.
- Raise and lower the rates at which banks borrow (through one mechanism called the Federal Funds rate).
- Expand its balance sheet by (essentially) printing currency and buying bonds.
For the sake of brevity today, generally speaking, the Fed cuts rates when unemployment is too high and raises rates when inflation is too high (remember the dual mandate).
Yet, for four decades, the Federal Reserve has provided more and more liquidity by steadily lowering rates. And yet, for four decades, growth has been, by and large, strong and unemployment has been, by and large, reasonably low (with some exceptions).
This introduced a strange dynamic where each time the Fed cut rates, it would cut much more deeply than when it would raise rates … hence, rates fell over a long period of time.
This is, in essence, just an expansion of liquidity. If a consumer would want to borrow $10,000 at 5 percent, they would probably be willing to borrow a much higher sum at 3 percent.
More broadly, in the last three years, for example, the Federal Reserve has created (through the Treasury) an additional $5 trillion (yes, trillion) out of thin air to help counteract the economic effects of COVID-19. In 2007/2008, the Fed introduced a bit over $1 trillion to counteract damage from the Global Financial Crisis. To be clear, some of this was absolutely needed and a good deal of it was remarkably effective.
And yet, as with anything, there are no absolute decisions, only tradeoffs. The obvious consequence is we have increased the money supply in the United States and, therefore, the value of our dollars has diminished. This, along with pent-up demand from COVID and supply chain disruptions, caused inflation to rise … and has created a very specific form of inflation referred to as monetary inflation.
As such, once it was clear inflation wasn’t “transitory,” the Fed finally began taking steps to reverse the cycle.
First it signaled it was slowing or stopping the expansion of its balance sheet, then it signaled it was going to raise rates and now it is in the process of raising rates.
As markets (both financial and physical) went up because rates went lower, markets go down when rates go higher. On the margin, the introduction of liquidity makes prices increase and the removal of liquidity makes prices decrease.
This is both logical and, in aggregate, a healthy move to begin focusing more intensely on the real economy and less intensely on the performance of markets.
Market performance during recessions
The question on the minds of many is therefore how far will the Federal Reserve go? Will the Fed bring inflation back down? Yes, I believe so. Will the Fed irreparably crush markets? No, I don’t believe so. Will the Fed push us into a recession? Well, possibly…
Which brings us to Chart 1: market performance during a recession, after a recession, and during “normal” times.
The period following recessions is quite good, however, as markets recover and generally with less of the unhealthy excesses that exacerbated the sell-offs in the first place. These periods are so good, in fact, that over the seven recessions from 1970, the year immediately following the end of the recession were slightly better than “normal times.”
Therefore, what to make of it all and what are investors to do?
- First and foremost, breathe. We have been through inflation, pandemics, wars, poor policies, high rates, low rates, high unemployment, low unemployment, and many other difficult environments before. Incentives drive behaviors and markets are driven by incentives. Those incentives haven’t changed and, as providers of capital, we, as investors, must still rely on those principles above all else.
- Second, recognize our human brain isn’t very good at market timing. Markets are down and if you have experienced the pain thus far, there is very little expected value in trying to time the market going forward. Even the most sophisticated investment organizations in the world can’t time markets very well.
- Third, go back to your plan. Market sell-offs are wonderful opportunities to refresh on goals and objectives. Refresh on how much you are spending and whether savings rates are high enough. Dare I say there might even be opportunities (as most equities are now less expensive and most bonds are now yielding more)?
- Fourth, review your fixed-income (e.g., bond) portfolio. The yield curve is now inverted which means shorter-term bonds are often yielding more than longer term bonds, and those shorter-term bonds are often associated with less risk. There are many other factors involved, of course, but where possible, consider shortening duration (the maturity of the bonds in your portfolio) if you haven’t done so already. Remember, inflation is not yet under control and it is unclear how soon that will happen.
In closing, take a moment to breathe, do not react emotionally, and use the difficult markets as an opportunity to reaffirm your long-term plan.
About the Author
Matthew Clayson is a Financial Advisor at Commonwealth Financial Group. He is a registered principal of, and offers investment advisory and financial planning services through, MML Investors Services, LLC, Member SIPC (www.sipc.org).